 By
Going public requires more than reaching a certain revenue target or attracting investor interest. Private companies often operate with flexible reporting schedules, concentrated decision-making, and financial processes that evolved alongside the business. A public company faces a different standard. Reporting, internal controls, governance, and recordkeeping must function consistently under greater scrutiny.
Financial Reporting Needs a Faster Rhythm
A private company may tolerate a lengthy month-end close or rely heavily on spreadsheets to reconcile accounts. Those habits become harder to sustain as reporting deadlines tighten.
Finance teams should test how quickly they can close the books and produce accurate financial statements. Reconciliations, accounting policies, and supporting documentation should follow repeatable processes rather than depend on a few employees knowing how everything works. Finding these weaknesses early gives management time to improve workflows.
Internal Controls Need Evidence
Growth can create awkward combinations of responsibilities. One employee might initiate a transaction, approve it, and maintain related records simply because the finance team was once much smaller.
Public-company preparation requires closer attention to segregation of duties, access permissions, approvals, and documentation. It is equally important to test whether controls operate consistently. A policy that exists on paper provides little value if employees routinely work around it.
Due Diligence Exposes Organizational Gaps
Preparing for a public offering can generate extensive requests for corporate records, financial information, contracts, ownership documents, and governance materials. Some companies use virtual data room software to centralize sensitive records and manage access during this process. The larger challenge is document quality. Missing agreements, outdated records, or conflicting versions can reveal weaknesses that require investigation.
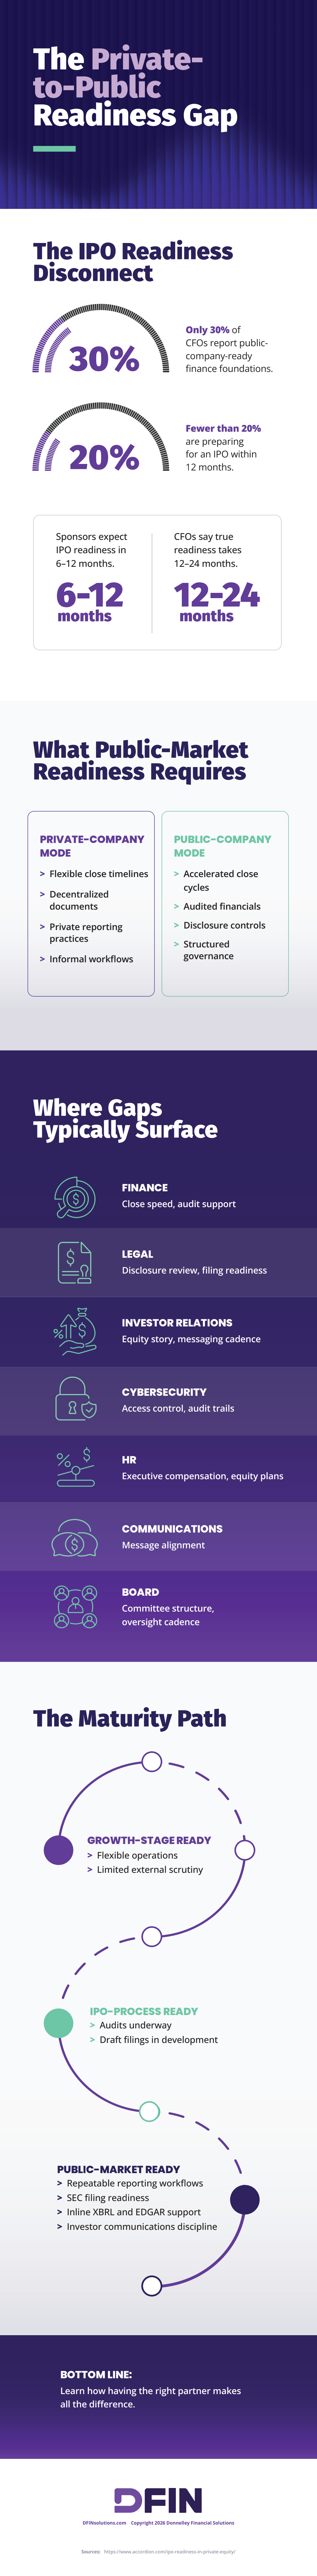
Closing the private-to-public readiness gap means changing how the company operates before public reporting begins. Stronger controls, faster financial processes, and organized records give management a clearer view of whether the business can meet its new obligations consistently. Look over the infographic below for more information.
Comments